How to Read a Merchant Statement (and Find Your Effective Rate)
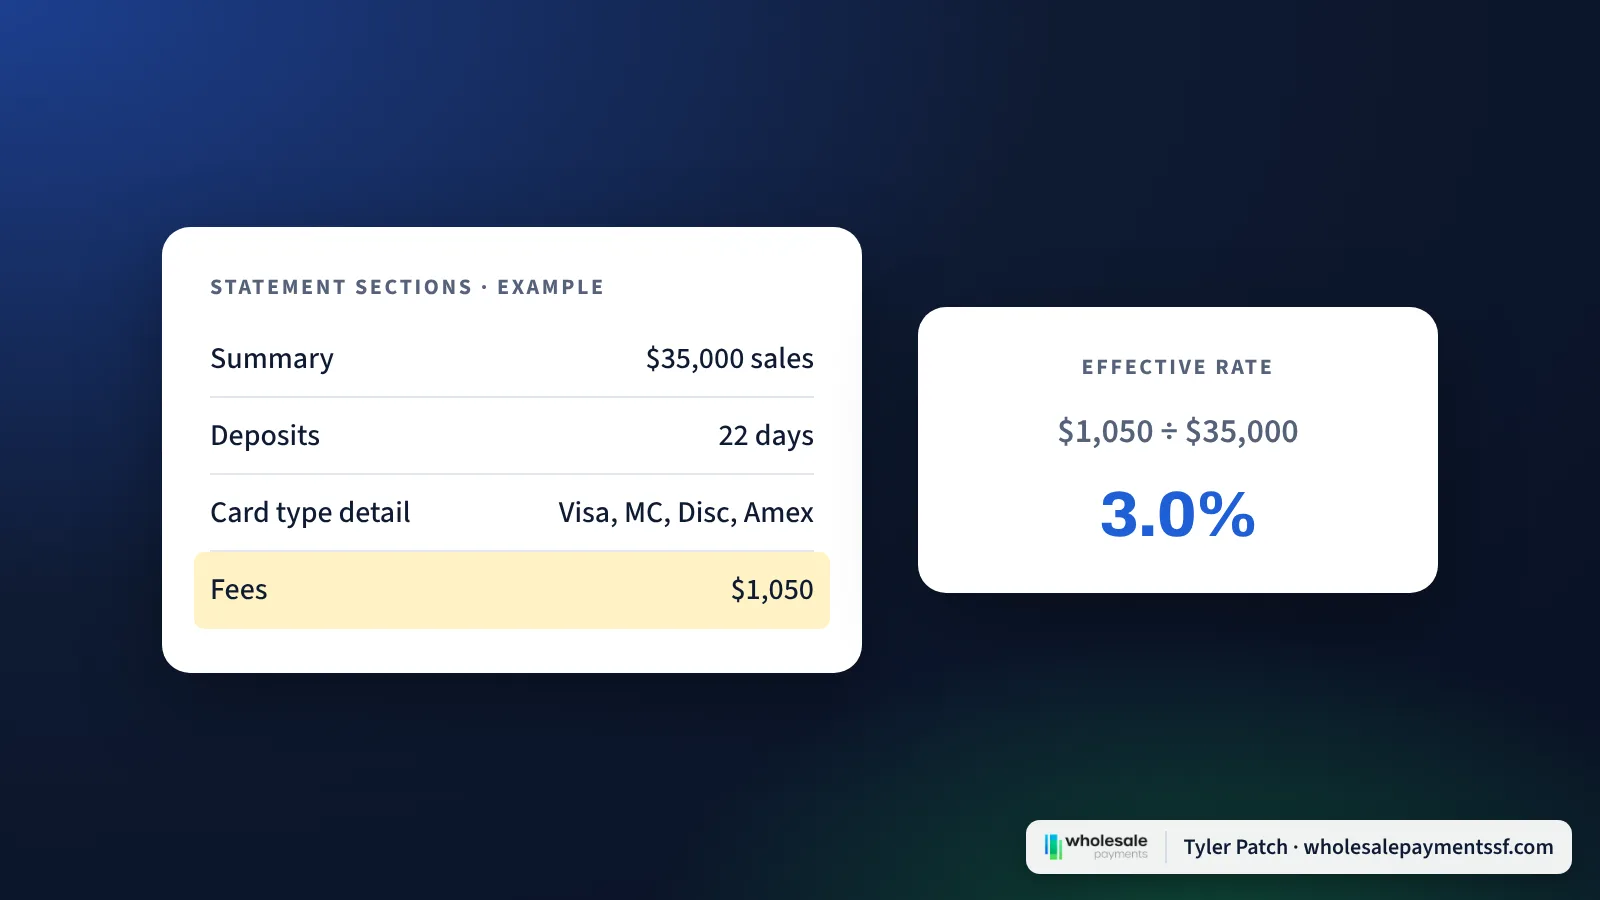
Merchant statements are confusing on purpose. This five-minute guide shows you where to look, what to add up and which lines to question.
The four sections on most statements
- Summary. Total card sales, refunds, chargebacks and total fees for the month.
- Deposits. What landed in your bank account each day.
- Card type detail. Sales broken out by Visa, Mastercard, Discover, Amex and debit.
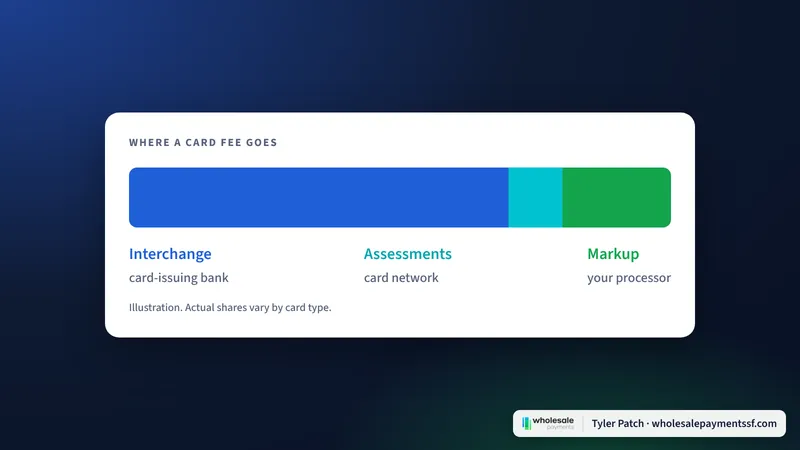
- Fees. Interchange, network fees, processor markup and monthly charges.
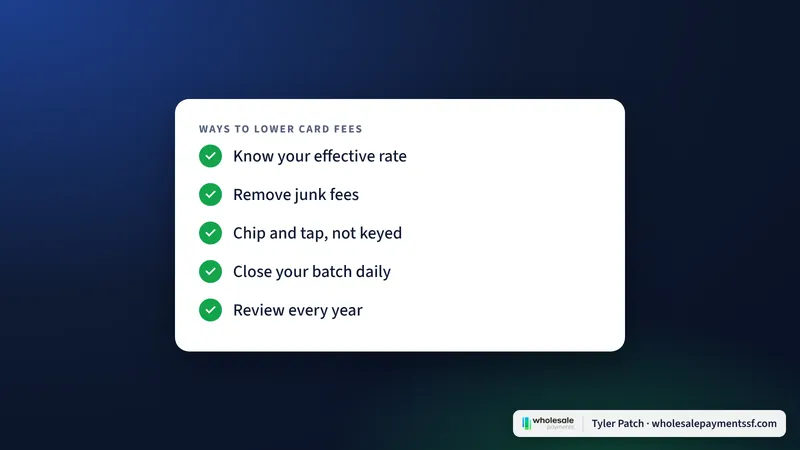
Find your effective rate in 3 steps
- Find total fees (sometimes called "total charges" or "fees charged") for the month.
- Find total card sales (sometimes called "total volume" or "gross sales").
- Divide fees by sales. $1,050 in fees on $35,000 in sales is a 3% effective rate.
Want to see what that costs per year? Use the card fee calculator.
Lines to question
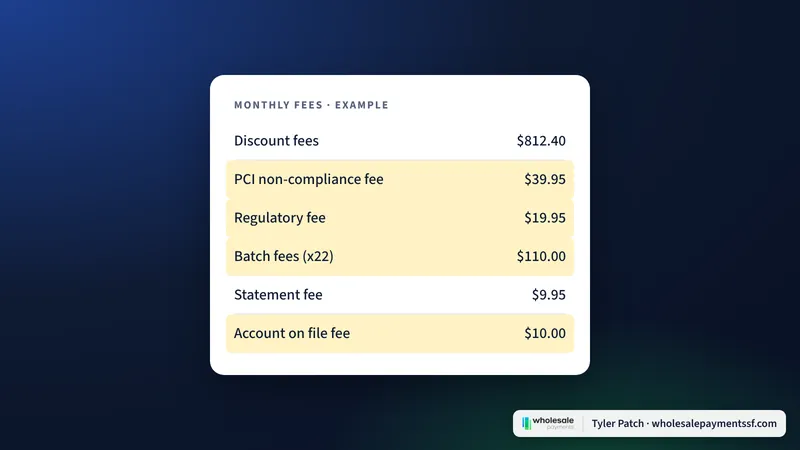
- PCI or non-compliance fees (see PCI compliance)
- Regulatory, security or "network access" fees
- Batch or statement fees
- Equipment lease or rental charges
- "Non-qualified" or "mid-qualified" surcharges on tiered pricing
- Annual fees that show up once a year
Our full list is in hidden credit card fees on your merchant statement.
Compare to last year
Pull a statement from 12 months ago and compare effective rates. Rates and fees often go up quietly with only a small notice printed on the statement.
Ask questions in writing
If a line doesn't make sense, ask your processor to explain it in writing and tell you whether it can be removed. If you compare offers, ask each provider to price your actual statement, with every fee listed, so you compare the same thing. A cash discount program is one more option to price out.
Frequently asked questions
How do I find my effective rate?
Divide total fees by total card sales on your monthly statement. For example, $1,050 in fees on $35,000 in sales is a 3% effective rate.
Why is my merchant statement so hard to read?
Every processor formats statements differently, and fees are often spread across several sections with vague names. A statement review can sort it out.
Who can review my merchant statement for free?
Tyler Patch, a Wholesale Payments Senior Account Executive based in Sioux Falls, reviews statements free for businesses anywhere in the U.S.
Questions about your own setup? Text Tyler.
General information only, not legal, tax or financial advice. Card network rules and state laws change, so confirm current rules before you change your pricing.